
Categories
Home Prices, Housing market, Interest Rates, Market Updates, Seattle Real Estate, Snohomish CountyPublished October 29, 2026
ARM Resets in 2027: What Washington Homeowners Need to Know
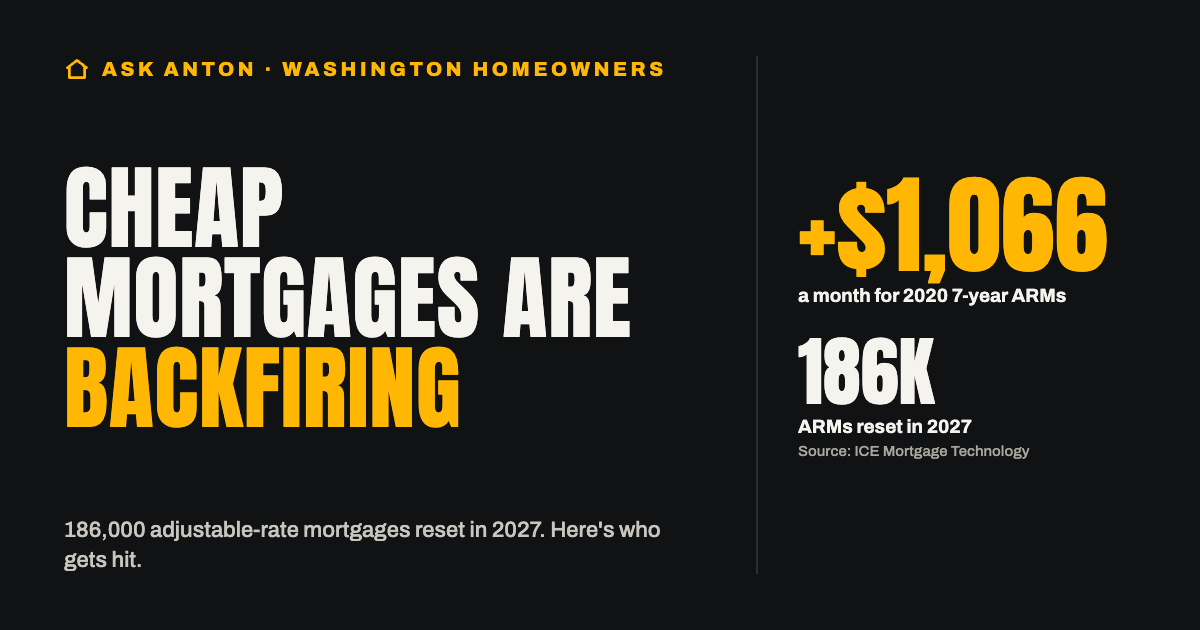
Key facts (October 2026): According to ICE Mortgage Technology, 186,000 adjustable-rate mortgages (ARMs) will reach their first rate reset in 2027. About 74,000 of them are 7-year ARMs taken out in 2020, and their median monthly payment is projected to rise by about $1,066. The typical 2027 reset adds about $645 a month, or 24%. There are about 3.1 million active ARMs in the U.S., 5.6% of all mortgages.
What is an ARM reset?
An adjustable-rate mortgage starts with a fixed rate for a set period, usually 5, 7 or 10 years (a "5/1," "7/1" or "10/1" ARM). After that, the rate adjusts based on a benchmark index plus a margin, usually once a year. Caps limit how much the rate can rise at each adjustment and over the life of the loan.
Why are 2027 resets so large?
Many of these loans started in 2020 and 2021, when rates were at record lows, often below 3%. They're now resetting while 30-year fixed rates are above 7%. A loan that started at 2.75% can reset to nearly 6% or higher, depending on its caps.
How many Washington homeowners are affected?
There's no official state count. Anton estimates between 3,500 and 7,000 Washington homes have mortgages resetting, based on the national total and the state's share of high-priced housing.
Is this another 2008?
No. During the mid-2000s housing boom, ARMs made up a much larger share of new mortgages. Today they account for about 11% of rate locks and 5.6% of active mortgages. Borrowers were qualified more carefully, and Washington homeowners hold substantial equity. In August 2026, Washington ranked 34th of the 50 states for foreclosure activity, with about 1 in every 5,905 housing units receiving a filing, according to ATTOM.
What about 2022 buydown loans?
In 2022, many buyers used temporary buydowns such as "2-1" or "3-2-1," which lower the rate for the first one to three years. Those payments have already stepped up to the full rate. For example, on a $500,000 loan at 7%, a 2-1 buydown payment rises from about $2,684 in year one to about $3,327 by year three, before taxes and insurance.
What should I do if I have an ARM?
- Find your loan's reset date, index, margin and caps in your loan documents.
- Estimate your new payment before the reset, not after.
- Talk to a lender about refinancing options early.
- If the new payment won't work, explore your options before you fall behind.
Is now a good time to buy new construction?
It may be worth a look. In September, 66% of U.S. builders offered sales incentives such as rate buydowns, and 38% cut prices, by an average of 6%, according to the National Association of Home Builders. Many incentive rates are well below today's 30-year fixed rate. Compare the full cost of the incentive, not just the rate.
Watch the full episode for Anton's complete breakdown, or call (425) 249-0214 with questions.
Anton Stetner
| Anton Stetner & RESG | Keller Williams North Sound
or another way